
We look at the OCR hold and what it means for your home loan.
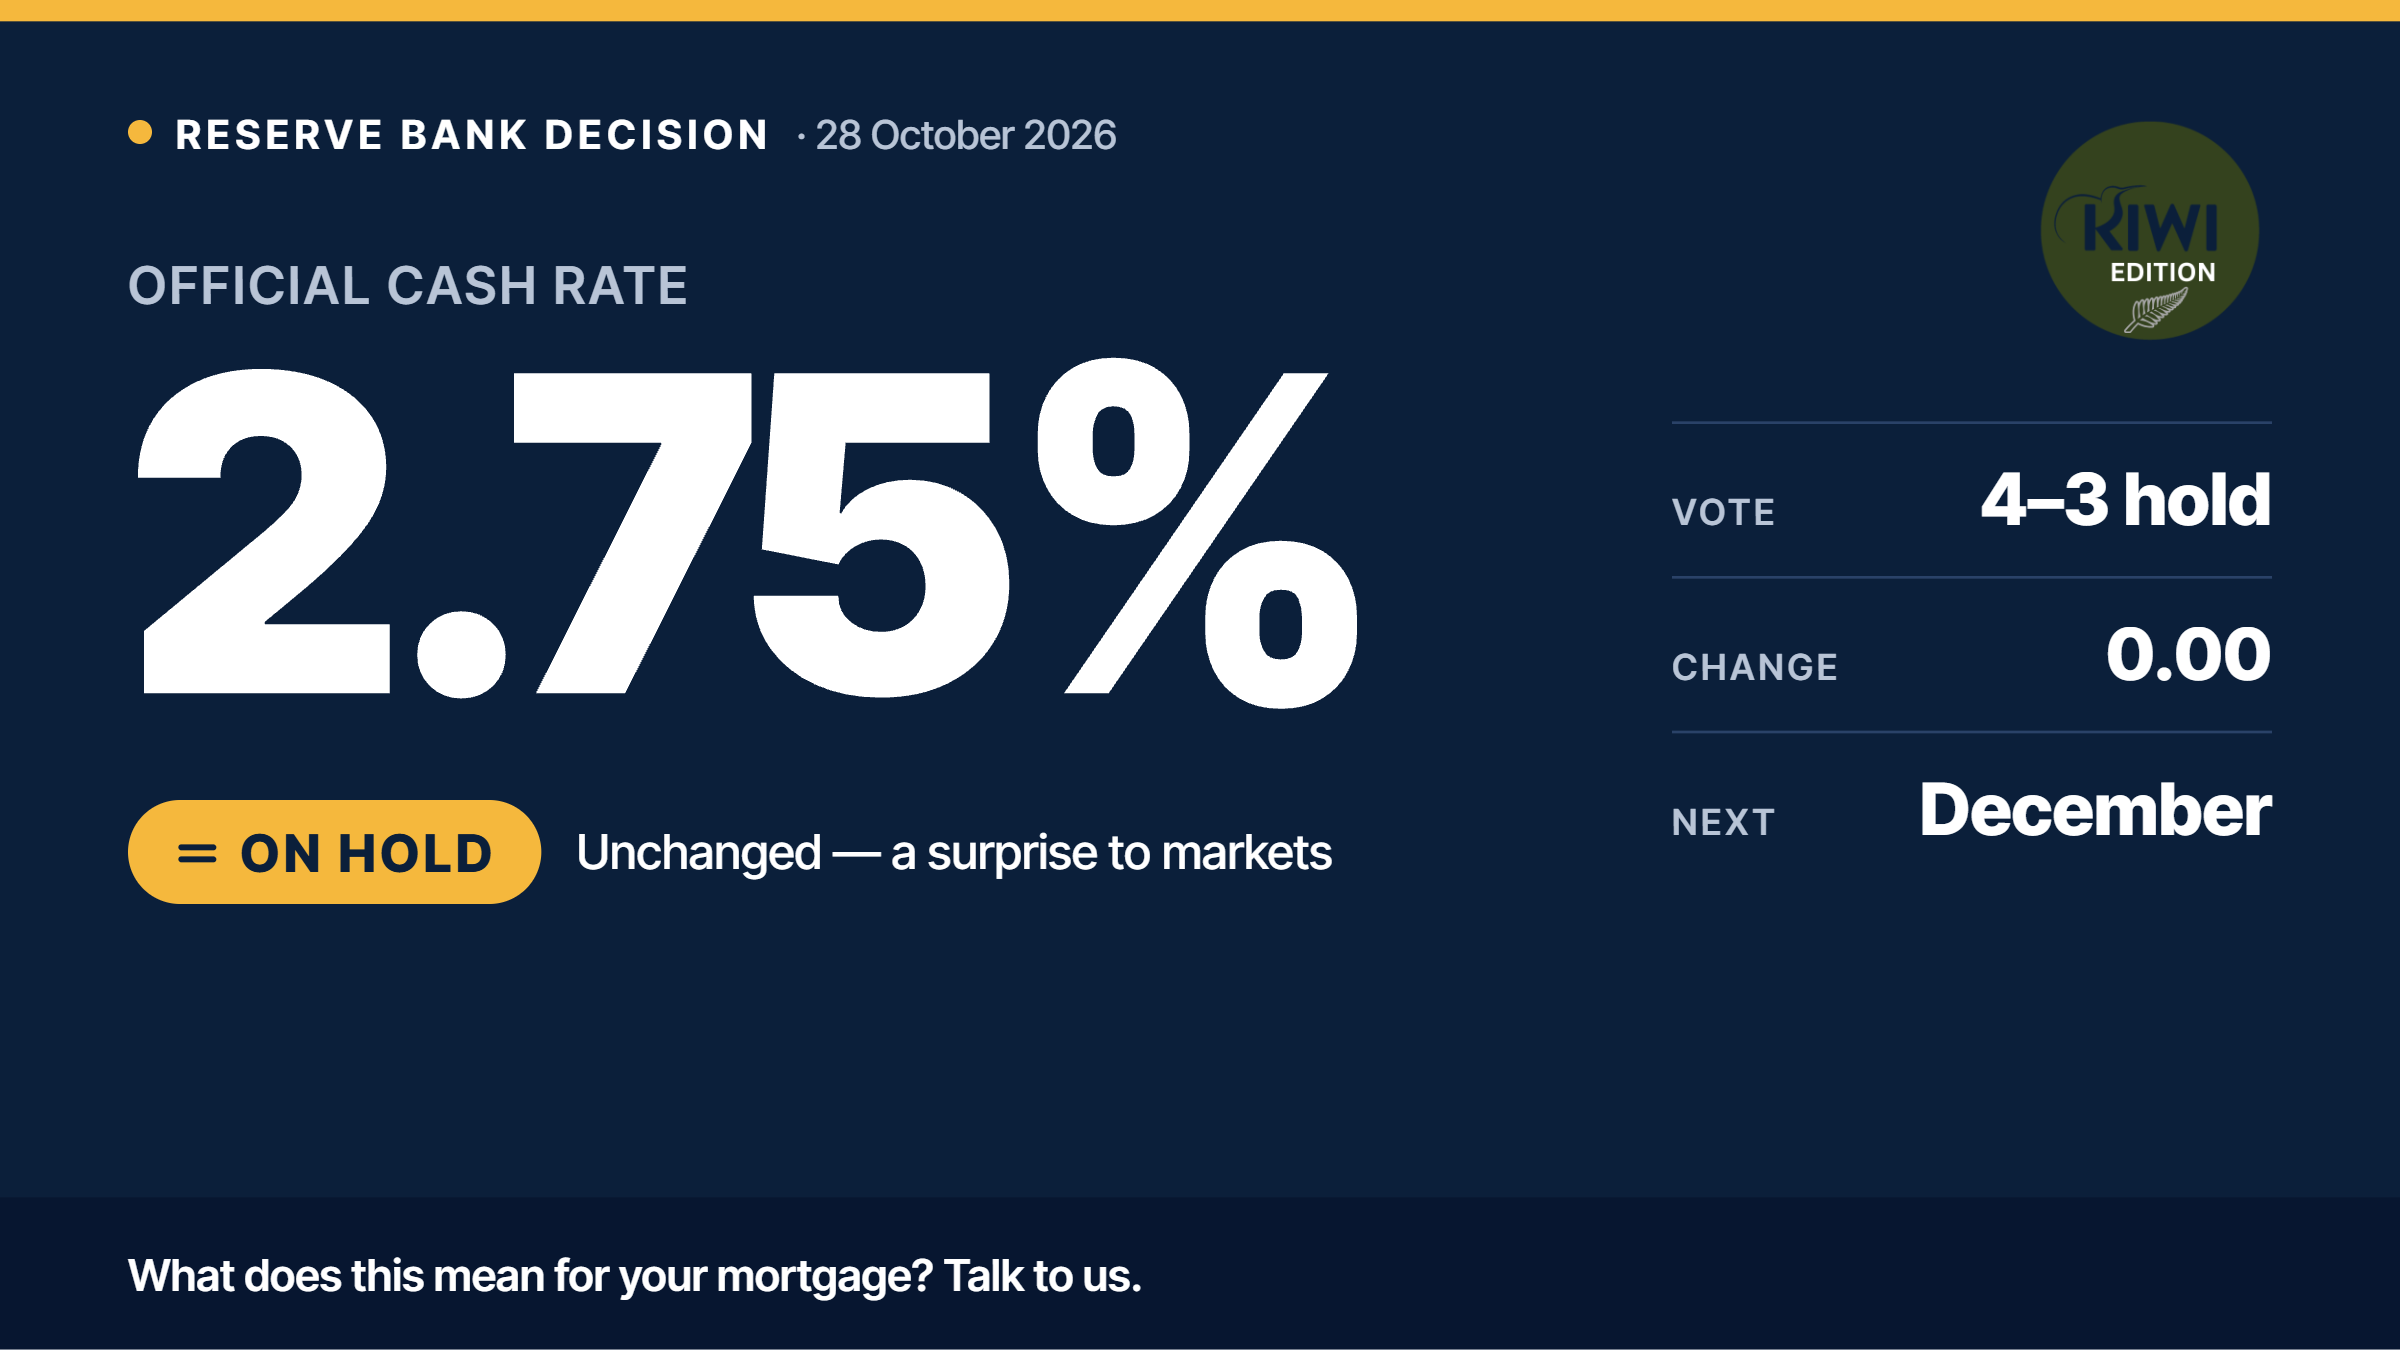
The Reserve Bank caught most of the market off guard yesterday, leaving the Official Cash Rate (OCR) unchanged at 2.75% in its October Monetary Policy Review. Almost every bank economist had forecast a 0.25% increase bringing the OCR to 3.00%. The financial markets had priced in roughly a 90% chance of a hike, and the banks had said the increase was already factored into their pricing.
A split decision
The decision for an OCR hold was not unanimous.
The Monetary Policy Committee voted 4–3, with Governor Anna Breman siding with three external members to hold, while three senior Reserve Bank officials voted for an increase. All seven agreed tighter policy is likely to be needed; they differed on timing, with the majority wanting more time to assess the rate rises made in July and September.
Breman has pushed back on criticism of holding while annual inflation sits at 3.7%, outside the mandated 1–3% target range. She says conditions for bringing inflation back to target remain favourable: inflation is too high, but it came in lower than expected. Inflation expectations have stayed well anchored, and higher fuel prices haven’t flowed through into other price categories as much as anticipated. The Bank also noted that subdued household spending is limiting businesses’ ability to pass on higher costs.
Why some economists are unhappy
The Reserve Bank isn’t obliged to follow market pricing or the general consensus, but it’s rare for it to go against expectations this clearly. Some of the criticism is fair comment.
You could also ask whether part of it comes from economists who made firm predictions in advance and got it wrong.
What it means for mortgage rates
In theory, if the banks had already built in a hike that didn’t happen, fixed rates should ease.
Realistically, few people expect that!
Yes, the OCR hold was a surprise but we also note that most of the banks economists still expect an increase in December, followed by another one or two in February and March next year.
It’s also worth remembering that fixed rates aren’t driven by the OCR alone.
Banks’ wholesale funding costs are heavily influenced by US bond yields and the New Zealand dollar, which fell almost a cent against the US dollar after the announcement.
Keep an eye on both – the way that the Reserve Bank manage the OCR and the US bond yields too.
Register HERE for all the latest updates too.
Apply your own thinking
Listening to bank economists is useful, but as this week showed they don’t always get it right.
We should always apply our own logic to what is happening, and to your personal situation. This is where a good mortgage adviser can add a lot of value.
They should help structure your lending so it fits within your risk profile and also lets you pay your home loan off faster.
That’s another reason to make sure you have the right home loan in the first place. Something many people don’t realise is how much the banks’ home loans differ beyond the headline rate.
If you’d like to learn more, get in touch and request our Special Report highlighting those differences.